
Mortgage Capacity Report
Obtain your Court compliant Mortgage Capacity Report within 24 hours, costing £99-£129 for most.
Please complete our contact form or email us at info@ukmortgageadvisors.co.uk for more info and a quote.
Get in touch for more info
How we can help
Working directly with clients and via our partnerships with Solicitors we have become one of the market leaders in producing timely and cost effective Mortgage Capacity Reports for new and existing clients throughout the UK.
FDR/Court compliant: This area of our practice has grown significantly and we now have Specialist Mortgage Advisors whose full time role is to produce fully FDR/Court compliant Mortgage Capacity Reports for use in divorce and separation settlements.
Cost effective: Our Mortgage Capacity Reports are one of, if not the most cost effective in the market, from £99 (for a no Mortgage Capacity Report) and costing £129 for most (single Mortgage Capacity Report).
Timely: We understand the importance of moving quickly, and for this reason Advisors will prioritise completion of reports and ensure they are completed within 1 working day.
How much do our Mortgage Capacity Reports Cost
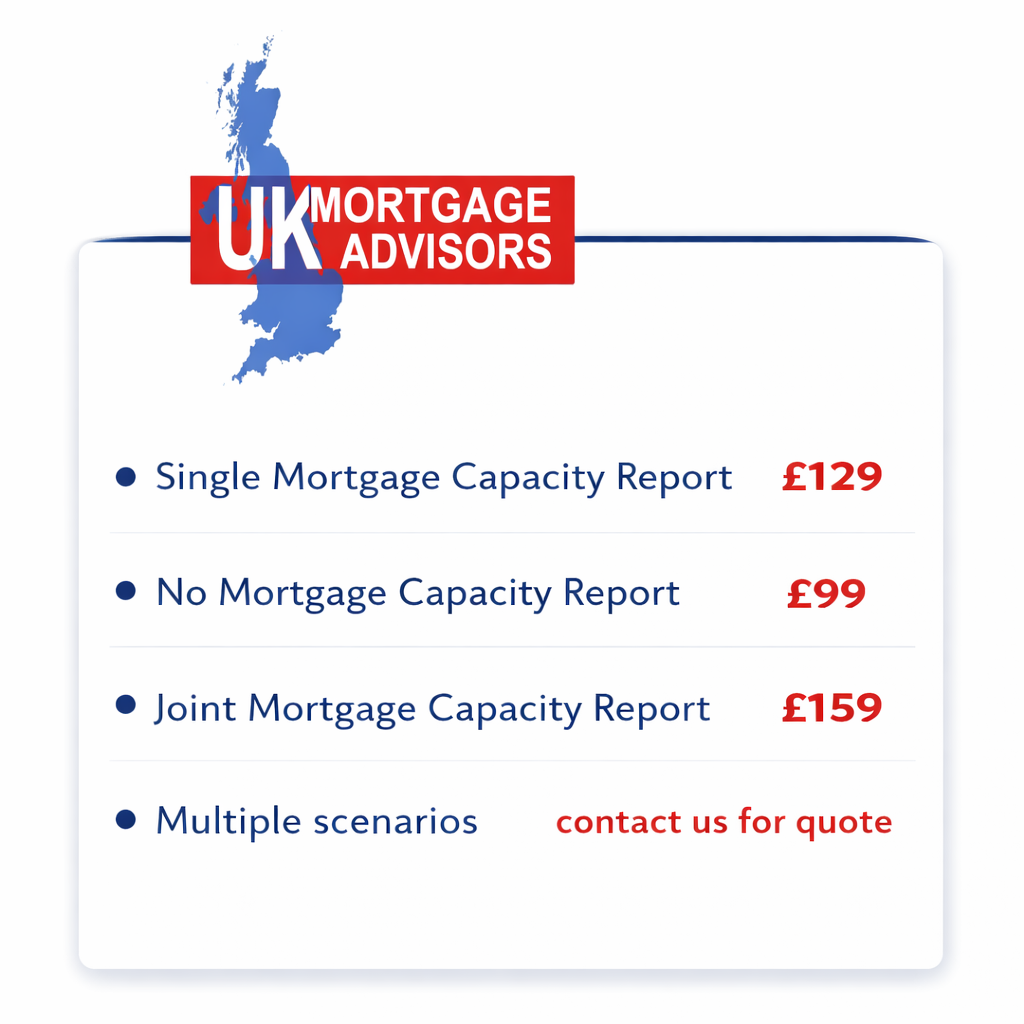
No Mortgage Capacity Assessment: £99
Single Mortgage Capacity Report: £129
Joint Mortgage Capacity Report: £159
Two Single Mortgage Capacity Reports: £199
Multiple Scenarios Report: Please contact us for a quotation, as this is a tailored report, costs can differ.
What is a Mortgage Capacity Report?
A Mortgage Capacity Report also known as a Mortgage Raising Capacity Report or Assessment is a document which provides details of the Mortgage you are able to obtain.
This can be completed for a number of scenarios including for joint and sole applicants.
This is usually required by the courts or mediators during the process of a divorce. The report could be required for both parties or just one.
Reports display the details of the person obtaining the report including the breakdown of their income and outgoings.
Followed by your maximum borrowing potential with each Lender, which will include all the main high street lenders as well as some Specialist Mortgage Lenders.
Solicitors and the Courts will typically require Mortgage Capacity Reports to cover the following four points:
(i) the information the calculation is based on i.e. your income and expenditure;
(ii) the maximum mortgage that the broker believes the applicant will be able to secure;
(iii) the term of that mortgage; and
(iv) the repayments that would be required on that mortgage on a repayment and interest only basis.
Mortgage Capacity Report for Divorce
Mortgage Capacity Reports are typically required during Divorce proceedings, and our reports can be used in the Courts for this purpose or any other Financial Dispute Resolution (FDR).
The purpose of the report is to usual detail your mortgage capacity as a single applicant.
The reason this is important, is because the report will in many cases have a direct impact in any divorce settlements.
Importantly the report will also detail if any applicant will be unable to obtain a Mortgage on their own or whether a property purchase is going to be affordable in the area they currently live in.
Different types of Mortgage Capacity Report
Single Mortgage Capacity Report: The most common scenario. A report for one person detailing their maximum Mortgage Capacity.
No Mortgage Capacity Assessment: A report which evidences someone is currently unable to obtain a Mortgage.
Joint Mortgage Capacity Report: A report which shows the Joint Mortgage Capacity of two borrowers together.
Two Single Mortgage Capacity Reports: Two Mortgage Capacity Reports detailing the borrowing capacity of two separate individuals.
Multiple Scenarios Report: This is a tailored report where the individual requires Mortgage Capacity Reports on a number of different scenarios. For example, how a likely change in circumstances could affect the maximum borrowing potential of a person. Such as a change to income or expenditure.
Benefits of a UK Mortgage Advisor Mortgage Capacity Report
Independent: It’s completed by a specialist who isn’t involved in the process, so both parties can have trust in the report.
Reliable: A CeMap qualified and FCA regulated Mortgage Advisor has to produce the report, so you can be sure they are accurate and provided by an experienced professional.
Detailed: The reports Mortgage Advisors provide are usually around 6-8 pages long and provide a full breakdown of all the information used for the Lenders to make a decision on the maximum borrowing. There is also a breakdown of what the party is able to borrow with each individual Mortgage Lender, high street a specialist.
Time: Obtaining a report from each individual lender would take a great deal of time. A Mortgage Advisor who is experienced in obtaining these reports can complete these requests with accuracy usually within 24-48 hours.
Useful: When you have agreed a settlement you will then be well equipped and know exactly what properties you can afford to buy. As the Mortgage Capacity Report is much more detailed than you would otherwise have if buying a property ordinarily.
What is the process?
Choose a report: Let your Advisor know which report you require. If you are unsure of this you can of course speak to the advisor or your Solicitor first.
Speak to a Mortgage Advisor: who will complete a short fact find on you and find out about your income and your outgoings.
Research: Your Mortgage Advisor will go away and obtain your maximum borrowing figures with a large number of high street as well as specialist lenders. So you can be sure that you will know your minimum, median and maximum borrowing potential.
Production of your Report: Your Mortgage Advisor will compile the report and include all the information which Mortgage Lenders consider when making their maximum borrowing decisions. As well as your maximum borrowing capacity with each lender.

What is considered when assessing how much you can borrow?
Your Mortgage Advisor will need details of your basic income, and any of the following if applicable:
- Self-employed earnings for the last 2 years. So your Net Profit and/or your Salary and Dividends if your Business is a Limited Company
- Bonus payments, commission and overtime
- Special rates for Contractors including IT and CIS Contractors
- Foster income
- Maintenance income – private arrangement
- Benefit income including, child benefit, working & child tax credits
- Pension or investment income
- Foreign currency income
- Casual employment for example zero hours contracts
The outgoings that lenders will consider when assessing your affordability are, but not limited to:
- Maintenance payments & Childcare
- Number of dependents
- Credit and Store Card Balances
- Monthly Payments for any Loans and Finance agreements, including Vehicle finance/Lease agreements
- Student Loans
- Council tax
- Travel costs
Any future changes to your income and expenditure which are likely to affect your ability to repay your Mortgage.
Affordability: Generally speaking, how much can I borrow?
This is the number one question and one of our Mortgage Advisors will be able to give you the exact figures.
It’s dependent on a number of factors including the lender, the size of your deposit and of course your income and regular outgoings. But to give you a rough answer in the simplest form, lenders will allow you to borrow up to around 4.49 to 5 times your income.
Other FAQ’s
Can I use your Mortgage Capacity Report for Divorce proceedings?
Yes, our Mortgage Capacity Reports can be used in Divorce proceedings and will be used by the courts/mediators and your Solicitor when deciding on what will be a fair settlement.
How long are Mortgage Capacity Reports valid for?
The courts will typically accept Mortgage Capacity Reports produced within the last 3-6 months.
If yours is older than this, the Courts or your Solicitor will likely require you to obtain a refreshed, up to date report.
UK Mortgage Advisors reports will not have an expiry or validity period detailed, it is purely down to the Courts to determine when your report stops being valid due to its age.
How much do Mortgage Capacity Reports cost?
Our Mortgage Capacity Reports usually cost between £99-£129. The Mortgage Advisor assigned to your enquiry will give you a definitive non-obligatory quotation during your first contact.
A standard single mortgage capacity report is what applies to most applicants which costs £129 total.
How long does the process take?
Once the Mortgage Advisor has reciepted all the information requested from you, your Mortgage Capacity Report will typically be produced within 24 hours.
Do I need to book an appointment or attend a meeting?
No, we appreciate that Mortgage Capacity Reports usually needed to be completed as quickly as possible. So our Advisors will deal with requests on demand, and there is no need for a meeting or appointment.
Mortgage Advisors will communicate via any means best for you. Usually the process can be completed entirely by email.
Why do I need a Mortgage Capacity Report?
As part of the Divorce process the Court will usually be the ones to prescribe that a Mortgage Capacity Report will be required for either one, or both parties.
The purpose of this is to give the Court a full view of your financial positions. A Mortgage Capacity Report will indicate whether or not you are able to afford a property purchase in your sole names.
In many cases a Mortgage Capacity Report will directly affect any divorce settlements.
What is a joint Mortgage Capacity Report for Divorce?
A Joint Mortgage Capacity Report can either mean a report based on two applicants, demonstrating the borrowing power of two people together. Or two individual Mortgage Capacity Reports for two people. Regarding the latter, we define this as two single Mortgage Capacity Reports.
Do you need documentation?
Whilst documentation isn’t always necessary, if you could have the following to hand or provide this it would assist your Mortgage Advisor in ensuring the report is as accurate as possible:
- Latest 3 Months Payslips
- If self-employed – your latest 2 years tax returns/SA302’s
In addition, the following documents may help you to provide the most accurate figures:
- Latest years P60
- Latest 1 months bank statement

We can help! Contact us to discuss obtaining a Mortgage Capacity Report
Speak to one of our qualified, regulated and highly rated Mortgage Advisors, which specialise in obtaining Mortgage Capacity Reports. Simply complete our short enquiry form and we will get one Mortgage Advisor that is local to you and which specialises in your case, to give you a call. They can answer any other questions you have, provide you with a free non-obligatory quote and/or talk you through the process in greater detail.
All our Mortgage Advisors hold the CeMap qualification (Certificate of Mortgage Advice & Practice) and are Regulated by the Financial Conduct Authority.

Check out our Blog
Follow us on Social Media or click the following link for the latest insightful articles and blog posts
ukmortgageadvisors.co.uk is an Information only website. None of the information provided constitutes advice. Advice should always be tailored to the individuals needs, which we do not do by providing general information.
Your information will only be used to provide one qualified and regulated Advisor which specialises in your needs with your contact details. We are registered for Data Protection purposes with the Information Commissioners Office.
All of our content is written by qualified and current Mortgage Advisors to ensure our information is as up to date and accurate as it can be.
Every Advisor we work with is regulated by the Financial Conduct Authority and authorised to give Financial Advice. We cannot be held accountable for any individual Advice an Advisor may give you. But if you do have any complaints at all, we of course want to know so we can act on it.